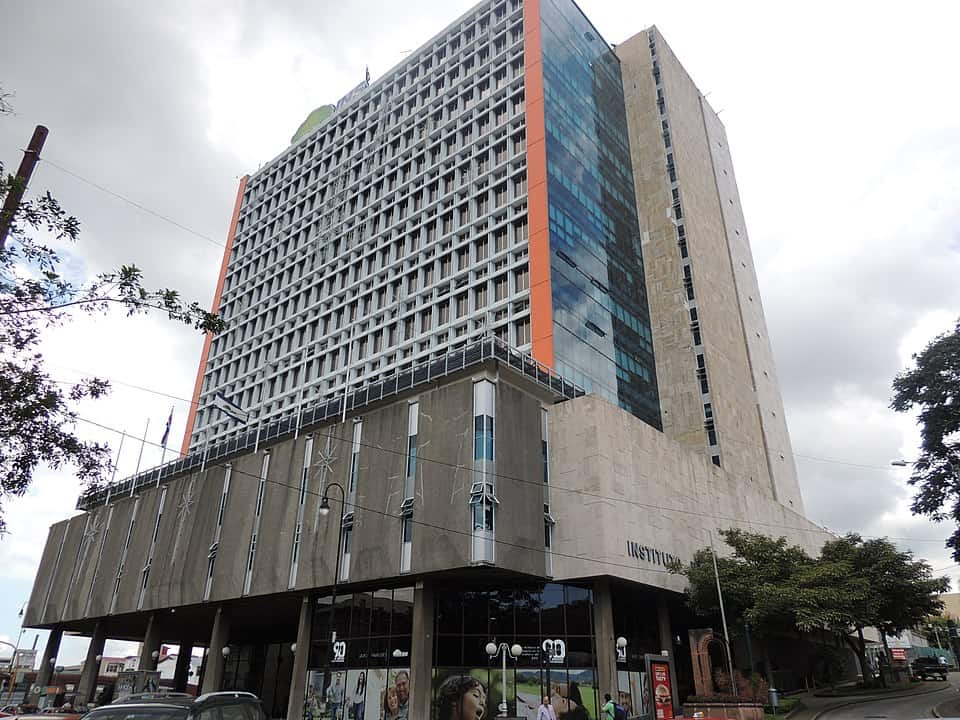
ABOUT four years ago the National Insurance Institute (INS) brought out a new homeowners’ policy, known in Spanish as Hogar Comprensivo.
Several drawbacks with the new comprehensive homeowners’ policy make some people prefer the old-fashioned Hogar Seguro 2000, a fire and natural disasters home insurance policy: First, no wooden houses can be insured. Second, the contents MUST be insured.
About 15 years ago, when Costa Rica shook nicely several times (insurance agents like the occasional ’quake!), we learned that block or brick houses may be severely damaged in a ’quake, but the contents will be quite unaffected.
So if you own a non-combustible house, you probably will not want to insure the contents, but the homeowners’ policy obliges you to do so, and you have to submit a complete list of household effects, with values of each item, and the makes, models and serial numbers.
HOGAR Seguro 2000 home fire and natural disaster policy is used for singlefamily dwellings. It can’t be used for commercial or industrial buildings, apartments, duplexes, etc., for which there is another type of policy.
The home fire policy can be used for stand-alone, semi-detached, or adjacent houses, as well as residential condos of the type where there is a large tract of land with several houses within – not the type where you have apartments stacked like pancakes.
The home fire policy has four sub-coverages: “A” is for fire and lightning; “B” covers damage caused by strikes, vandalism, hurricane, cyclone, explosion, smoke, falling objects and vehicles; “C” pays for damage caused by floods and landslides; and “D” covers natural disasters: ‘quakes, tremors, volcanoes, tsunamis, etc.
You can take A coverage by itself, A+B, A+CD, or complete coverage A+B+CD.
Rates are based on a percentage of the value and include 13% sales tax, and an optional inflationary factor whereby every year, on the anniversary of the policy, INS increases the insured value following an index of construction costs.
Coverage A 0.0760%
A+B 0.1013%
A+CD 0.2500%
A+B+CD 0.2753%
THE corresponding rates must be applied to the value of the building. The value INS requires is the estimated cost of rebuilding, less depreciation.
Depreciation is estimated at 2% per year for wooden houses, or 1% per year for masonry houses – starting, of course, from when the house was built or extensively redone.
If you want to insure the contents of your house, you must put a value on the objects based on depreciated value. The same rate for the house applies to the contents.
For example, a house is worth ¢10 million, and the contents are worth ¢1 million. Coverages A+B+CD are needed. The rate is 0.2753% per the above table. It would cost ¢27,530 ($65) to insure the house and ¢2,753 ($6.50) to insure the contents. Total yearly premium would be ¢30,103 ($71.50).
OK, but who puts a value on the house? You do, esteemed reader! Based on what? Sometimes people want to use the purchase price. Not good! A purchase price usually includes uninsurable components like the value of land, the location, the view, security, etc.
Other times, when people have recently purchased a property, they want to use the value the notary put on the purchase agreement. No good, either, as it includes the value of land and other uninsurable factors – and also because notaries often “fiddle” the value (downward) to reduce the amount their client must pay for the property transfer tax.
Well, how about using the value listed with the Municipality for the property tax? Not recommended, because property tax is levied basically on the value of land, with some consideration for the value of improvements.
SO, how do you arrive at the insurable value?
If you have recently built the house, use the cost of construction.
If the house is older, you can have it appraised, or – less expensively – invite your friendly builder over for a cuppa and ask him or her how much “this type of construction” is costing at this time, per square meter or square foot. Multiply the answer by the dimensions of your house, subtract 1-2% per year for depreciation and you’ll arrive at a pretty accurate figure.
Some advice: try to get the value as accurate as you can. If you overstate the value, you are throwing premium money away, because if your house falls down or burns down it is INS’s option to pay you the insured value, or to repair or rebuild, and if you over-insured, they will repair or rebuild.
If you understate the value, INS will certainly not repair or rebuild: they will “apply coinsurance,” which means they will determine by what percentage you understated the value, and pay the claim based on the remaining percentage. For example, if you have a house worth 100 and insure it for 70, it is to be assumed that you are willing to carry 30% of the risk yourself. If you have a claim, INS will pay the remaining 70% of the cost of the repair.
IN paying claims, INS will subtract the deductible established on the policy. The deductibles are fixed, standard and nonnegotiable.
For A coverage, there is no deductible. On B coverage, the deductible is ¢20,000 ($47.17) per claim, and for hurricane damage it is 20%. For C and D coverages the deductible is 1% of the total insured amount, with a minimum of ¢50,000 ($117.92).
INS’s track record in paying claims on this type of policy is quite good. The institute has a team of adjusters who deal fairly quickly and efficiently with day-today claims.
However, most of the claims against the Hogar Seguro 2000 policy are for earthquake damage. When ‘quakes have hit Costa Rica, INS has had a lot of claims, overwhelming the team of adjusters.
In 1990 and 1991, when there were two fairly lively shakes, they hired more than a dozen additional claims adjusters and, with their help, most of the claims were settled within 60 days.
SOME people doubt whether INS would be able to settle claims from a major earthquake or a huge hurricane like Mitch.
To dispel doubts: INS is by far the largest insurance company in Central America – in fact, one of the largest in Latin America, is financially solid, and – most importantly – it re-insures worldwide a large percentage of the risk. It has never been put to the ultimate test, but it has a lot going for it so it may be ranked “safe.”
Our purpose is to give the reader a better understanding of homeowners’insurance in Costa Rica. The opinions and viewpoints expressed are those of the writer, and do not necessarily represent the official position of the National Insurance Institute (INS).